
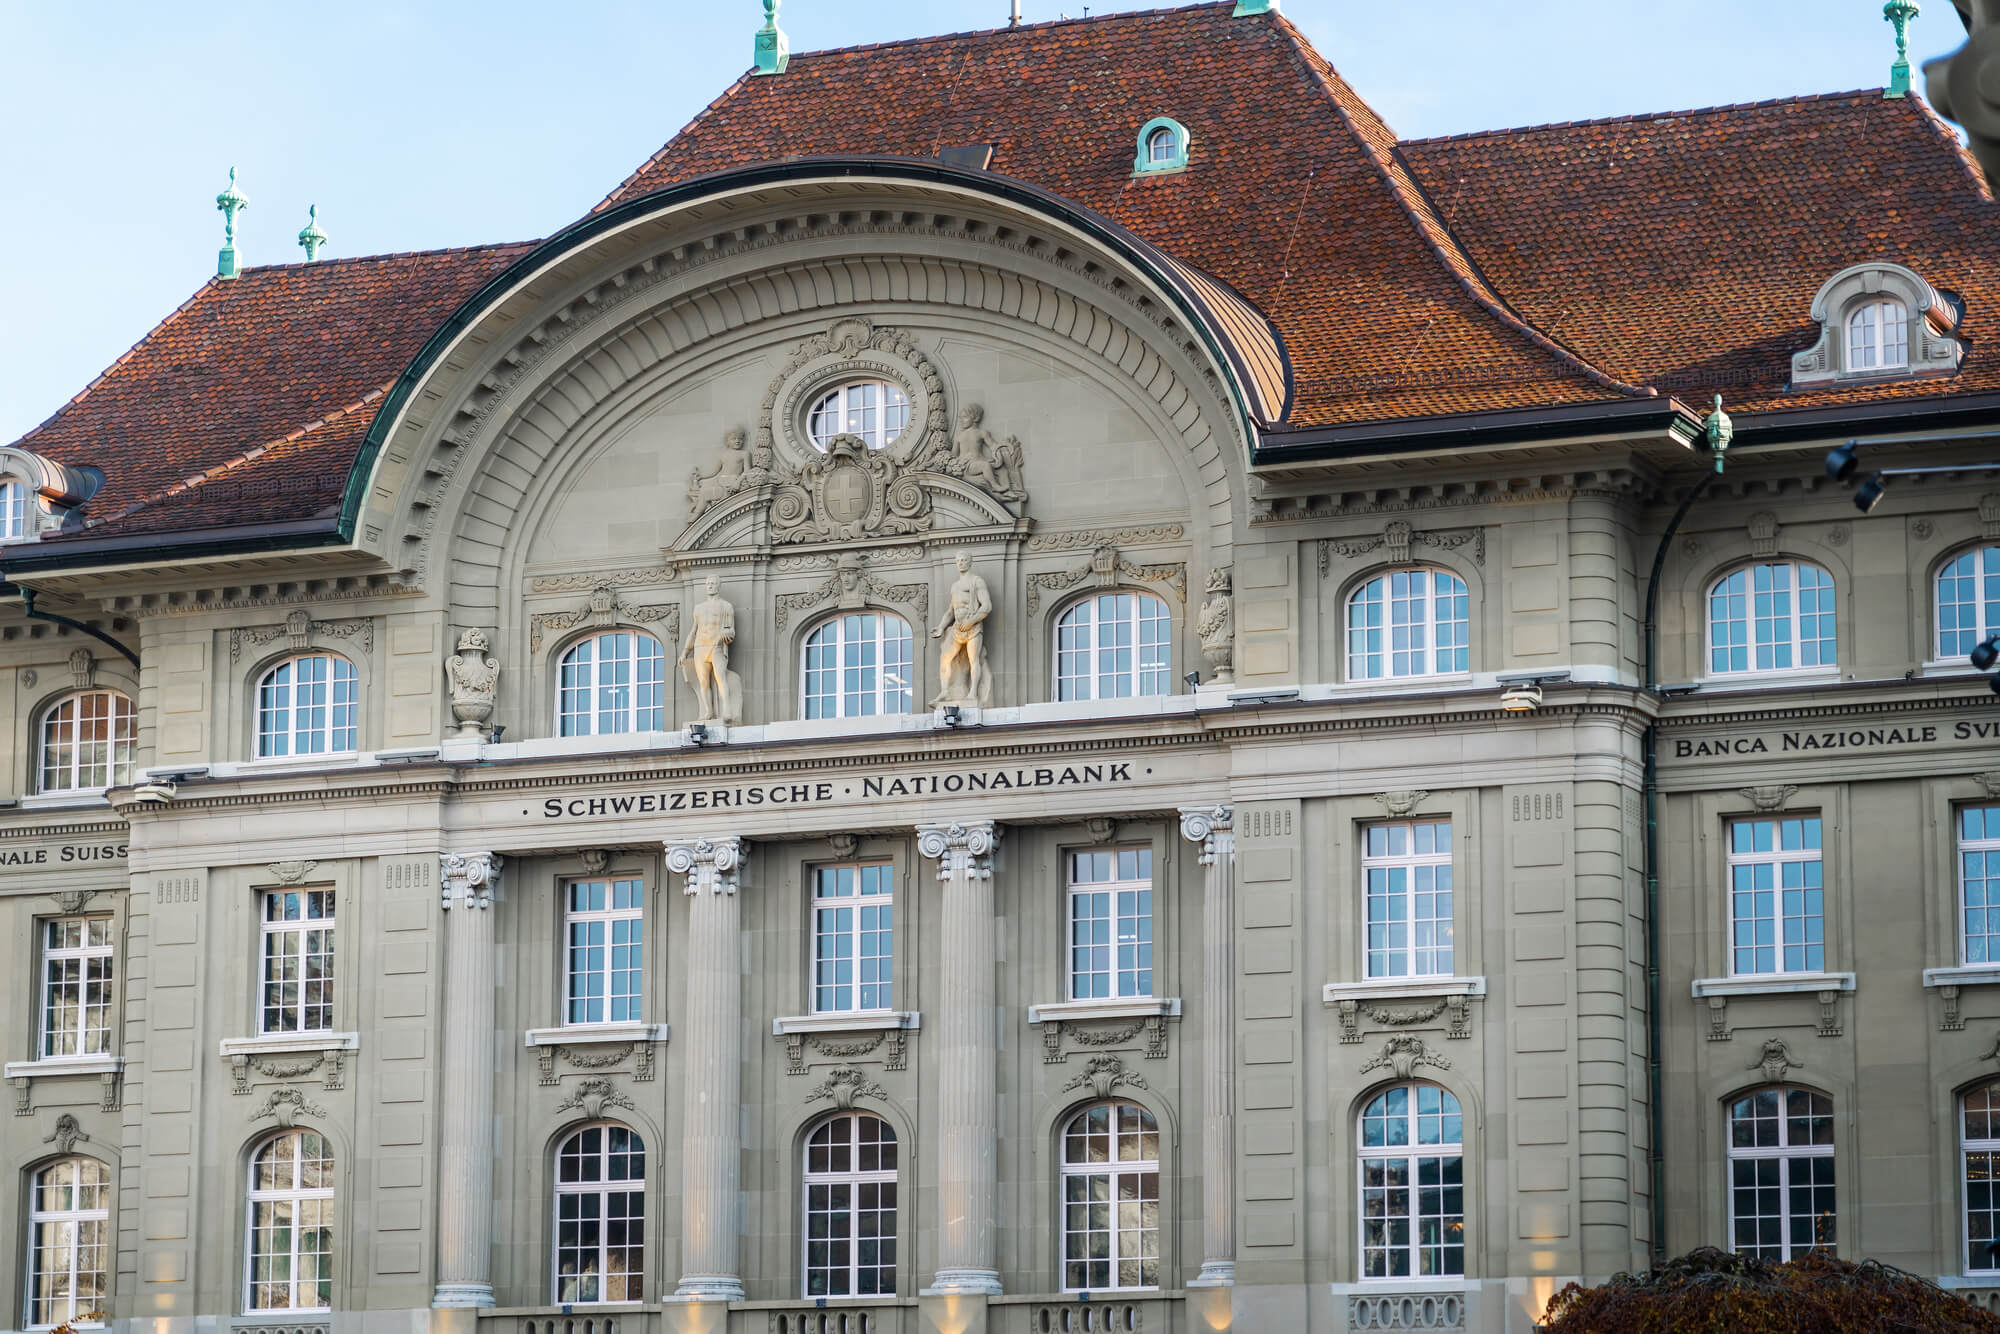
Petra Tschudin sits on the Governing Board of the Swiss National Bank (SNB). She sees large stablecoins as a burden on monetary policy. According to Tschudin, stablecoins without a link to the two-tier financial system make transmission harder. They also increase the burden on central banks.
The SNB is Switzerland's central bank, and its mandate is to ensure price stability. To do so, it steers the money market through its policy rate. This impulse then reaches the economy through bank loans and interest rates. Economists call this path transmission. In the two-tier system, the central bank first issues central bank money. Commercial banks then pass it on to households and companies. Stablecoins, however, are private tokens, usually pegged to the US dollar or the franc, that circulate outside this system. In late September 2026, Tschudin spoke at the forecasting conference of KOF, the economic research institute of ETH Zurich. Before that, the central bank had devoted a special topic to stablecoins in its 2026 Financial Stability Report.
How stablecoins weaken the SNB's interest rate channel
The mechanism behind the warning starts with bank deposits. If households and companies move money from their bank accounts into stablecoins, commercial banks lose part of their funding. As a result, bank lending volumes fall, and the shift also affects interest rates. If the central bank later changes its policy rate, the move works less directly. This is because it steers borrowing costs less effectively. So the strength of monetary policy depends on deposits that stay in the banking system. Tschudin's presentation slides address large stablecoins and a missing link to the two-tier financial system. According to the slides, both hamper "among other things, the transmission of monetary policy."
Tschudin is describing a scenario, however, not a current disruption. In her account, the burden on central banks only rises if large stablecoins emerge far removed from the existing system. At the same time, the central bank does not reject new developments. It welcomes innovation in payments if it makes them safer and more efficient. It also sees modernizing the two-tier system as sensible. "When we introduce innovations, we really need to ask what consequences they have, and how they should be regulated," the SNB board member said. In her view, design and regulation are therefore decisive. Private forms of digital money must not jeopardize the SNB's ability to fulfill its mandate.
Why a stablecoin franc is not automatically a franc
The SNB's second objection concerns the uniformity of money. After all, stablecoins operate outside the central bank system. Following Tschudin's argument, a stablecoin franc is therefore not automatically worth the same as a real franc. This puts pressure on the principle that money is uniform everywhere. It follows that the value of such a token depends on the issuer, not on the central bank.
"If we end up with big stablecoins that are really far removed from the existing two-tier financial system, then that's a situation which increases the burden on central banks in fulfilling their mandate."
- Petra Tschudin, member of the SNB Governing Board
The quote refers to tokens that move far away from the existing system. Tschudin thus sets a narrow condition. In addition, the SNB worries about settlement between banks. Commercial banks settle their claims with each other in risk-free central bank money, and large stablecoins could affect this foundation. Notably, the central bank frames its criticism around integration and regulation. It does not call for a ban. For future franc stablecoins, this sets clear standards: close integration with the two-tier system and effective regulation.
In its own report, the SNB calls stablecoins a niche phenomenon
The central bank's assessment of the situation is comparatively sober. In its 2026 Financial Stability Report from the summer, the SNB describes stablecoins in Switzerland as a "niche phenomenon." In its view, they currently pose no risk to financial stability. The tokens are "typically pegged to established currencies such as the US dollar or the Swiss franc," the report says. So far, they play only a minor role in Swiss payments. Several banks and financial companies are working on a project for a digital franc. According to the news agency AWP, it is still only in the testing phase.
Nevertheless, chapter 5.1 of the report names specific weaknesses. These include volatile backing, which can make redemption at par harder, and interconnection with the rest of the financial system. Moreover, a large outflow of bank deposits into stablecoins could amplify instability in the banking sector during a crisis. What gets lost here is the link to the speech. And it is exactly this outflow that forms the starting point of Tschudin's transmission chain. In other words, the report describes the current state, while the speech outlines the scenario of wider adoption.
Furthermore, the SNB considers international coordination of regulation important. Issuers could launch stablecoins in less regulated jurisdictions, which could then see wide use in Switzerland. The US shows how differently the timelines run. The US President signed the GENIUS Act in July 2025. However, the law only takes effect 120 days after the final implementing rules, and no later than 18.01.2027. These rules still existed only as drafts in spring 2026.
Helvetia and the FINIG revision set the Swiss framework
The central bank offers its own alternative to the private tokens. Since December 2023, it has been testing a central bank digital currency in Project Helvetia Phase III. The test targets financial institutions and runs on SIX Digital Exchange (SDX). Six banks originally took part: Commerzbank, BCV, Basler Kantonalbank, Hypothekarbank Lenzburg, UBS and ZKB. At the end of June 2025, the SNB extended the project until at least mid-2027 and added an RTGS link. This link allows tokenized assets to settle in SNB money via the SIC payment system. BX Digital is also getting a production connection to SIC. According to the SNB, however, the extension is not a commitment to introduce wholesale CBDC permanently.
Meanwhile, the federal government is working on the legal framework. In October 2025, the Federal Council opened the consultation on the revision of the Financial Institutions Act (FINIG). It ended in early February 2026. The draft provides for two new license categories: the payment instrument institution and the crypto institution. The payment instrument institution replaces the existing fintech license. Under the new rules, client funds can be segregated in bankruptcy, and the CHF 100 million limit no longer applies. In the future, only a payment instrument institution licensed by FINMA may issue Swiss stablecoins.
Yet it will take time before this framework applies. The Federal Council's dispatch will come in the second half of 2026 at the earliest. So far, there is no known publication. After that, parliament still has to debate the bill, and a possible referendum period follows. The SNB board member is thus warning at a time when Switzerland still lacks a framework for franc stablecoins.