
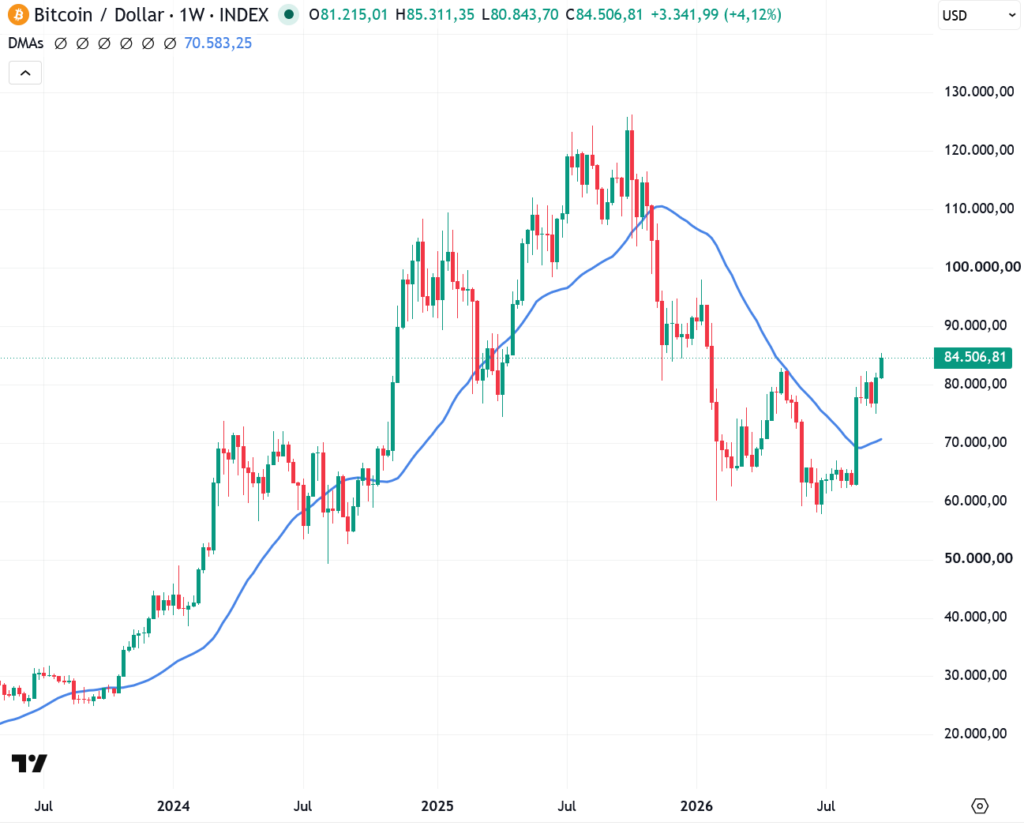
Bitcoin has rebounded from a low of around $60,000 to roughly $84,000. Has the 2026 Bitcoin bottom already been reached? Ten signals suggest that a sustainable bottom is becoming increasingly plausible.
Since reaching an all-time high of more than $126,000 in October 2025, Bitcoin has at times lost more than half of its value. In July, Bitcoin briefly fell below $60,000. Since then, the picture has changed. Bitcoin first recovered above $70,000 and most recently climbed to around $84,000.
Whether the market has already put in its low cannot be answered with certainty. However, several signals from price action, capital flows, derivatives markets, onchain data and the macroeconomic environment now suggest that the bottoming process may already be well advanced.
1. What Supports a 2026 Bitcoin Bottom: Bitcoin Absorbs Bad News
A market bottom often reveals itself less through good news than through how the market reacts to bad news. On September 15, the Digital Asset Market Clarity Act failed to clear the required procedural threshold in the U.S. Senate. One day later, the Federal Reserve raised its policy rate by 25 basis points to 3.75%–4.00%.
Bitcoin initially came under pressure but subsequently recovered strongly, climbing back to around $83,000. The market increasingly appears able to absorb negative news without triggering another major sell-off.
2. ETF Demand Returns on Pullbacks
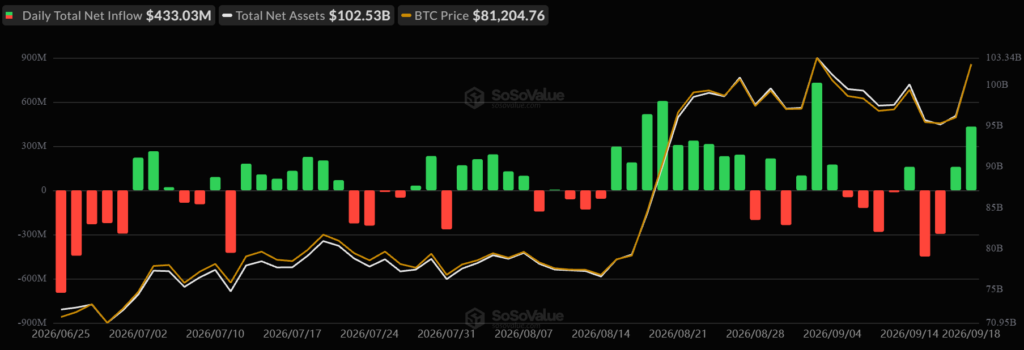
An interesting pattern is also emerging in U.S. spot Bitcoin ETFs.
On September 15 and 16, the products recorded net outflows of around $746 million. Over the following two trading days, however, flows turned positive again, with around $484 million returning to the products. This is not yet a new sustained inflow trend. But it shows that institutional demand remains present at lower price levels.
3. Selling Pressure Is Easing
Onchain data point to declining sell-side pressure. In its latest Week Onchain report, Glassnode shows that the Sell-Side Risk Ratio fell to around seven basis points per day in early September, down from roughly 16 basis points at the August peak. At the same time, the share of realized profits attributable to long-term holders declined from 88% to 47%.
Put simply, despite the recovery, realized selling pressure is significantly lower than it was just a few weeks ago.
4. The Bottom Signals Were Unusually Broad
Even more striking is the breadth of the capitulation. Glassnode combines a range of onchain, market and valuation metrics in its 45-indicator cycle model. By the end of June, 82% of these indicators were in their respective coldest zones. Such a broad concentration of bottom signals is unusual and has since started to recede. This does not prove that the bottom is in, but it suggests that a significant part of the market-wide reset may already have taken place.
5. The Derivatives Market Is Not in Euphoria Mode
The futures market also appears less overheated than during previous rally phases. While Bitcoin open interest remains high, it has not expanded explosively in recent weeks. At the same time, funding rates remain at moderate levels.
Leverage is therefore still present, but without the acceleration typically seen during late-stage periods of market euphoria.
6. The Technical Market Structure Has Turned
When assessing whether the 2026 Bitcoin bottom is already behind us, the technical market structure is also crucial. During the rebound, Bitcoin reclaimed the important 200-week moving average and broke the sequence of lower swing highs. That is a much more direct bottoming signal than the more abstract global liquidity thesis.
7. The Debasement Trade Remains Intact
At the same time, the structural backdrop for scarce assets is improving. The U.S. Treasury has at least doubled the size of its buybacks of longer-dated government bonds from September onward, from a maximum of $2 billion to at least $4 billion per operation. At the same time, the Treasury plans net marketable borrowing of $739 billion in the third quarter and another $628 billion in the fourth quarter.
The buybacks are officially intended to improve market liquidity and do not change the government’s high financing needs. For Bitcoin, a key structural driver therefore remains intact: a growing supply of government liabilities is meeting an asset with a fixed long-term maximum supply.
8. Crypto Liquidity Has Not Disappeared
There is still substantial capital within the crypto ecosystem. Stablecoin market capitalization stands at around $305 billion and has increased slightly over the past 30 days.
Stablecoins are not a direct leading indicator for Bitcoin. However, they show that digital dollar liquidity did not leave the ecosystem to the same extent during the downturn. If risk appetite returns, a sizeable liquidity base therefore remains available.
9. The Classic Altcoin Mania Is Missing
Market breadth also looks different from the late stages of previous crypto cycles. Bitcoin currently accounts for around 59% of total crypto market capitalization, while the Altcoin Season Index stands at only around 50 out of 100.
So far, there has been no pronounced rotation out of Bitcoin and into increasingly smaller and more speculative assets. The kind of euphoria that accompanied previous cycle peaks has yet to emerge in the same form.
10. Institutional Adoption Continues
While prices corrected sharply, the institutional integration of digital assets continued. More banks, asset managers, exchanges and market infrastructure providers are expanding offerings for trading, custody, tokenization and blockchain-based settlement.
Bitcoin is also benefiting from this trend. Beyond its role as an investment asset, BTC is increasingly being used as collateral and as a financing instrument within institutional structures. The price correction has not stopped this expansion so far.
This is not an immediate bottom signal. However, it suggests that fundamental adoption is continuing independently of the short-term market cycle, broadening Bitcoin’s structural demand base.